Westinghouse Electric Is Taking Nuclear Back to the Stock Market. At 63, Where He Buys the IPO Decides How Much of His Social Security Turns Taxable.
Capital gains from a Westinghouse IPO won't trigger Social Security benefit withholding, since the earnings test only counts wages and self-employment income.
A $25,000 short-term gain in a taxable brokerage account can add $25,000 of income plus $7,400 of newly taxable Social Security to a return.
A large taxable gain at 63 can raise Medicare Part B and Part D premiums at 65, since surcharges use income from two years prior.
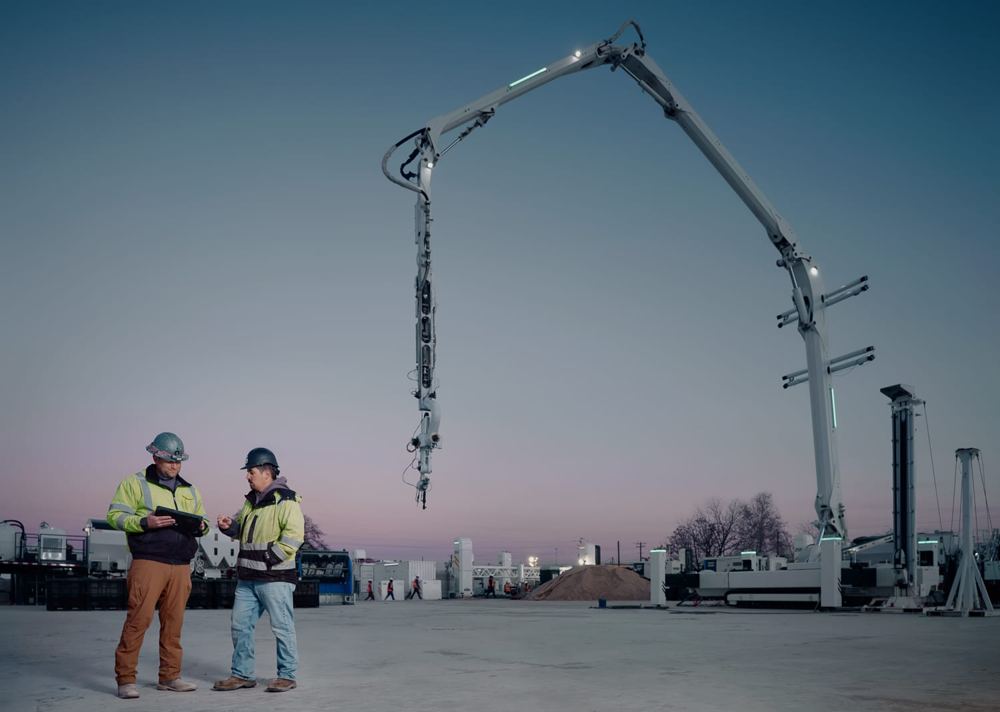
Westinghouse Electric confidentially submitted a draft registration statement for an IPO on July 31, nearly a decade after cost overruns at some of its projects pushed the company into bankruptcy. Canada's Cameco and Brookfield Renewable Partners, which acquired Westinghouse in 2023, are taking another run at the public markets while data centers revive demand for nuclear power. The confidential filing contains no public share price or offering date, and Westinghouse is not guaranteed to complete the listing.
A 63-year-old collecting Social Security may still want a piece of the comeback. The first question is not whether an IPO gain will stop his monthly check. It will not. The more interesting question is which tax return will eventually see it.
Because he claimed before his full retirement age (FRA) of 67, the retirement earnings test applies. In 2026, Social Security withholds $1 in benefits for every $2 of wages or net self-employment income above $24,480. Investment gains do not enter that calculation.
Social Security specifically excludes capital gains, interest, pensions, annuities and other investment income from the test. A hypothetical $50,000 Westinghouse gain therefore would not cause the agency to withhold his monthly benefits. It also would not matter while it remained on paper. Purchasing the stock and watching it appreciate creates no taxable income. The tax consequence begins when he sells and realizes the gain, receives a dividend or takes a taxable retirement-account distribution.
If you've saved over $1,000,000, this guide is for you. The last thing you want in retirement is to run out of money, you want your money to generate lasting income while you enjoy your life.
The separate exposure comes through combined income, sometimes called provisional income. The formula includes adjusted gross income (AGI), tax-exempt interest and half of the year's Social Security benefits. For a single filer, benefits begin becoming taxable above $25,000. Above $34,000, the taxable share phases toward a ceiling of 85%. Joint filers encounter those stages at $32,000 and $44,000.
Consider a single retiree receiving $20,000 in annual Social Security benefits and a $30,000 pension. His combined income is already $40,000, making approximately $9,600 of his benefit taxable. Now suppose he realizes a $25,000 short-term Westinghouse gain:
In a taxable brokerage account, combined income rises to $65,000, and the taxable portion of his benefit reaches its $17,000 ceiling. The gain therefore adds $25,000 of its own income plus another $7,400 of taxable Social Security to the return. Inside a traditional individual retirement account, the trade creates no immediate tax. Future taxable withdrawals enter ordinary income and feed the same Social Security formula. The appreciation also loses the possibility of favorable capital-gains rates. For someone born in 1963, required minimum distributions (RMDs) begin at 75.
Inside an established Roth IRA, qualified distributions generally remain outside AGI once the five-year requirement and age-59½ rule are satisfied. The gain can therefore leave the taxable portion of Social Security unchanged.
The 1.85 multiplier does not apply to every dollar of the $25,000 gain. It operates only while additional income is pulling more Social Security into the taxable column. Once 85% of the benefit is taxable, each additional dollar contributes only itself.
The retiree cannot simply move $25,000 of pension income into a Roth IRA before the IPO. Contributions require taxable compensation, and the combined traditional and Roth IRA contribution limit for someone 50 or older is $8,600 in 2026.
He could convert money from a traditional IRA, but the taxable portion of that conversion would raise AGI immediately and could make more Social Security taxable in the conversion year (we walked through why the quiet years before RMDs are often the cheapest time to build that Roth space in a free guide here). The Roth also owns the entire downside. If Westinghouse falls after the offering, the loss cannot offset other capital gains or produce a deduction. In a taxable account, capital losses can offset gains and as much as $3,000 of ordinary income annually, with unused losses carried forward.
A large taxable gain at 63 can also affect Medicare premiums at 65. The income-related surcharge for Part B and Part D generally uses modified adjusted gross income from two years earlier. A 2026 gain can therefore help determine his 2028 premiums if it pushes him above the applicable threshold. Holding the shares longer than one year may produce a lower capital-gains rate, but it does not keep the gain out of AGI, the Social Security formula or the Medicare calculation. Before pursuing an allocation, three details matter:
Model the gain as unrealized, short-term and long-term income.
Measure how much Social Security is already taxable before adding the sale.
Weigh the Roth's shelter for gains against the loss deduction available in a taxable account.
Westinghouse is trying to leave its bankruptcy years behind. The investor cannot control whether its shares complete the same comeback, but he can decide which tax return participates in it.
Contact editorial@247wallst.com for any questions or corrections.