The Strategist Who Wanted 8,400 on the S&P 500 Just Cut His Number, and It Is Not Because Earnings Got Worse
Yardeni cut his SPY year-end target from 8,400 to 7,900, blaming a 10-year yield near 5% compressing multiples, not deteriorating earnings.
NVDA alone holds nearly 8% of SPY, and with U.S. corporate profits up 23% year-over-year, the bull case depends on AI earnings leverage carrying the market.
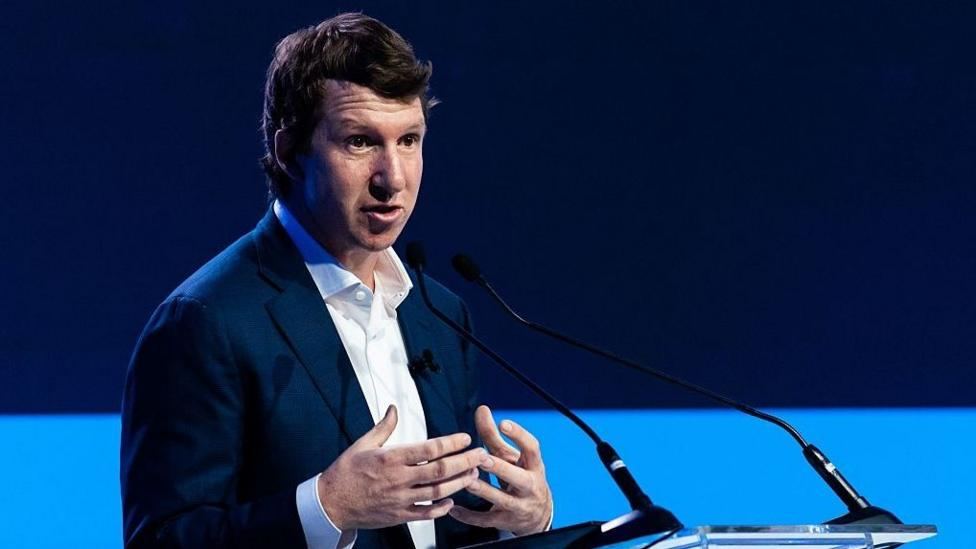
A Wall Street strategist trimming an index target on the same afternoon the Federal Reserve signals a fresh hiking cycle sounds like capitulation, yet the substance reads differently. Ed Yardeni, who had been making one of the loudest bullish calls on the Street, walked his year-end S&P 500 number down from 8,400 to 7,900, a level he quickly noted would still print a record high. Yardeni moved the old 8,400 target to mid-next year.
For holders of the SPDR S&P 500 ETF ( NYSEARCA:SPY ), the distance is real. SPY closed at $754.13 on September 16, 2026, down 2.4% over the past month even as the fund remains up 10.59% year to date. A target cut driven by discount rates behaves very differently from one driven by shrinking profits, and the market is pricing the difference in real time. This is a call about what a dollar of earnings is worth, and that is where individual investors most often get the signal wrong.
Yardeni's framing matters. He went from 8400 to 7900. 7900 would still be a record high, though barely.
A strategist who pushes a target out along the calendar delivers a materially weaker bearish signal than one who lowers a target permanently. The destination is unchanged. Moving Yardeni's 8,400 from December to June is closer to saying the runway is longer than saying the plane will not fly, according to Yardeni Research.
The mechanism Yardeni described is a discount-rate call. "If it kind of hangs around 5%, I think that's going to erode the valuation multiples somewhat. Earnings, I think, are going to be fantastic."
How do you continue to grow a seven-figure portfolio in retirement? The last thing you want is to run out of money, you want your money to generate lasting income while you enjoy your life.
Learn seven strategies high net worth investors use with new report: The Seven Secrets of High Net Worth Investors from Fisher Investments. Get your guide here (sponsor)
When the risk-free rate rises, the present value of future corporate cash flows falls, so investors pay fewer dollars for the same dollar of earnings. Strong profits and a lower index target can coexist without contradiction. The 10-year Treasury sat at 5.01% on September 16, and the 30-year at 5.35%, right in the zone Yardeni flagged as multiple-compressing.
Total U.S. corporate profits reached $4.8 trillion in the second quarter, with reported year-over-year growth of 22.8%, according to the Bureau of Economic Analysis. The pressure sits squarely in the denominator.
Yardeni reads the Summary of Economic Projections as the opening of a hiking cycle, with another move possible this year and one more next year. That view sits alongside a policy rate whose upper bound stands at 3.75%, well below the long end of the curve.
The tell is at the long end. The 10-year minus 2-year spread has narrowed to 0.27%, its lowest in the past year, while the VIX at 17.20 shows repricing without panic.
The bull case rests on Yardeni's arithmetic. Earnings growth is running well above trend, index concentration in mega-cap technology delivers operating leverage on AI demand, and a target of 7,900 still implies meaningful upside from current levels.
The bear case is the one Yardeni himself concedes: a 10-year yield anchored near 5% grinds valuation multiples lower even while profits climb. Hedging across horizons by trimming the near-term number while preserving the long-run one admits that timing is unknowable.
The variable that decides between them is the long end of the curve, not the policy rate. If the 10-year settles back into Yardeni's 4-to-5 zone, the multiple math works. If it stays pinned above 5, earnings will have to do all the lifting, and the market will feel heavier than the profit numbers suggest.
Contact editorial@247wallst.com for any questions or corrections.