Welspun Corp's euphoric investor reaction to US order comes with risks
Welspun will have to ensure that such order wins are repeated, especially from the US, for revenue visibility beyond FY29.
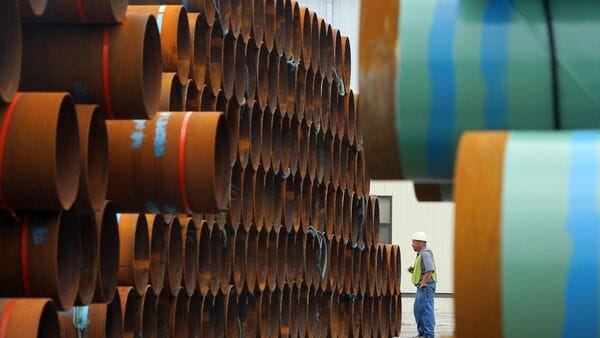
Welspun Corp.’s shares continued to gain on Monday, rising over 3%, following a 15% jump on Friday after winning the single largest order in its history worth $1.8 billion ( ₹ 17,200 crore) for supplying pipes from its US manufacturing facility. This pushes up the order book to ₹ 42,000 crore. The pipes will be used to carry over 3 billion cubic feet of gas from the Permian Basin spanning western Texas and New Mexico to the Gulf Coast.
Investors are naturally pleased with the improved revenue visibility. While the news is certainly positive, the Street’s immediate reaction seems to be disproportionate. The market capitalization rose by almost 50% of the order value, which seems to be on the higher side.
Plus, the financial benefits will not reflect immediately because the order is to be executed over FY28 and FY29. The management said on a conference call held after securing the mega order that the Ebitda margin in the US business is likely to be $250-300 per tonne.
Notably, this is not a recurring order. Welspun will have to ensure that such order wins are repeated, especially from the US, for revenue visibility beyond FY29. The US is the biggest contributor to the order book with a share of 60-65%. But the US orders and their subsequent execution may be subject to two factors, political changes in the US and the ever-evolving dynamics of crude oil and natural gas prices.
True, the current US president is more inclined towards higher oil and gas exploration, which leads to more demand for pipeline infrastructure. But this could change after the US elections in 2028 if the next president cares about global warming and shifts the focus to renewable energy.
Also, exporting pipes from India to the US is not viable due to import tariffs in the US. Welspun is relying on expansion of its US plant to cater to demand. Though the management believes that import tariffs under Section 232 cannot be rolled back easily and will mean good demand for their US pipe manufacturing facility, there is always uncertainty about the rate even if the tariff stays.
Furthermore, if conflicts such as the ongoing West Asia war are resolved, then it could lower crude oil and natural gas prices. If that happens, it could slow down new drilling and pipeline infrastructure investments in the US.
Even if it is assumed that the order flow continues unabated, the Welspun stock does not appear cheap. The management has guided for revenue of ₹ 20,000 crore and Ebitda of ₹ 2,850 crore for FY27.
Welspun’s market capitalization is ₹ 62,500 crore and it had a cash balance of ₹ 2,300 crore at Q1FY27-end, so its enterprise valuation (EV) works out to ₹ 60,200 crore. The EV/Ebitda multiple at FY27’s guided Ebitda works out to 21, which is not cheap.
Perhaps investors are factoring in the possibility highlighted by the management that doubling of FY27 Ebitda by FY30 is achievable if all of Welspun’s business geographies fire. This is a tall task as it would require a CAGR of almost 30% from FY27 onward, which is much higher than 15% over the past two years to FY26.