Francophone business leaders seek harmonised rules for cross-border payments
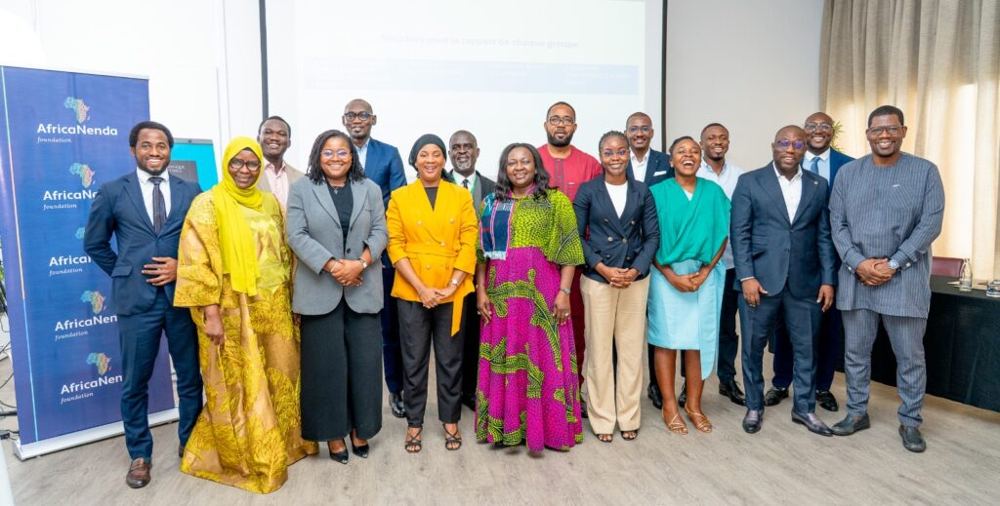
Business leaders in Francophone West Africa have called for harmonised financial regulations, improved access to settlement accounts and sustained engagement
Business leaders in Francophone West Africa have called for harmonised financial regulations, improved access to settlement accounts and sustained engagement between regulators and industry players to facilitate cross-border payments across Africa. The call was made at the Francophone Africa Leaders Forum on Enabling Cross-Border Payments held in Abidjan, Côte d’Ivoire. The forum brought together chief executives and senior representatives of 11 institutions, including banks, fintech firms, payment service providers and payment infrastructure operators. Participants identified regulatory fragmentation, restricted access to settlement facilities and inadequate consultation between regulators and private sector operators as major obstacles to efficient cross-border payments. They urged the establishment of a permanent platform for dialogue between regulators and industry players to ensure that policies and regulatory reforms reflect operational realities and emerging market needs. The participants at the event held on July 22, 2026, also called for mutual recognition of licences, harmonisation of Know Your Customer requirements and greater consistency in regulations across African monetary unions. They said the measures would reduce operational costs, encourage competition and improve access to affordable cross-border financial services. According to the forum, existing settlement arrangements, which largely restrict settlement accounts to banks, place licensed non-bank payment service providers at a disadvantage. The arrangement forces such providers to depend on banking intermediaries for settlement and foreign exchange transactions, resulting in additional delays, liquidity constraints and higher operational costs. The participants therefore recommended expanding access to settlement accounts for appropriately licensed non-bank providers and allowing supervised private sector operators to participate more directly in settlement arrangements. They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The call was made at the Francophone Africa Leaders Forum on Enabling Cross-Border Payments held in Abidjan, Côte d’Ivoire. The forum brought together chief executives and senior representatives of 11 institutions, including banks, fintech firms, payment service providers and payment infrastructure operators. Participants identified regulatory fragmentation, restricted access to settlement facilities and inadequate consultation between regulators and private sector operators as major obstacles to efficient cross-border payments. They urged the establishment of a permanent platform for dialogue between regulators and industry players to ensure that policies and regulatory reforms reflect operational realities and emerging market needs. The participants at the event held on July 22, 2026, also called for mutual recognition of licences, harmonisation of Know Your Customer requirements and greater consistency in regulations across African monetary unions. They said the measures would reduce operational costs, encourage competition and improve access to affordable cross-border financial services. According to the forum, existing settlement arrangements, which largely restrict settlement accounts to banks, place licensed non-bank payment service providers at a disadvantage. The arrangement forces such providers to depend on banking intermediaries for settlement and foreign exchange transactions, resulting in additional delays, liquidity constraints and higher operational costs. The participants therefore recommended expanding access to settlement accounts for appropriately licensed non-bank providers and allowing supervised private sector operators to participate more directly in settlement arrangements. They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The forum brought together chief executives and senior representatives of 11 institutions, including banks, fintech firms, payment service providers and payment infrastructure operators. Participants identified regulatory fragmentation, restricted access to settlement facilities and inadequate consultation between regulators and private sector operators as major obstacles to efficient cross-border payments. They urged the establishment of a permanent platform for dialogue between regulators and industry players to ensure that policies and regulatory reforms reflect operational realities and emerging market needs. The participants at the event held on July 22, 2026, also called for mutual recognition of licences, harmonisation of Know Your Customer requirements and greater consistency in regulations across African monetary unions. They said the measures would reduce operational costs, encourage competition and improve access to affordable cross-border financial services. According to the forum, existing settlement arrangements, which largely restrict settlement accounts to banks, place licensed non-bank payment service providers at a disadvantage. The arrangement forces such providers to depend on banking intermediaries for settlement and foreign exchange transactions, resulting in additional delays, liquidity constraints and higher operational costs. The participants therefore recommended expanding access to settlement accounts for appropriately licensed non-bank providers and allowing supervised private sector operators to participate more directly in settlement arrangements. They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
Participants identified regulatory fragmentation, restricted access to settlement facilities and inadequate consultation between regulators and private sector operators as major obstacles to efficient cross-border payments. They urged the establishment of a permanent platform for dialogue between regulators and industry players to ensure that policies and regulatory reforms reflect operational realities and emerging market needs. The participants at the event held on July 22, 2026, also called for mutual recognition of licences, harmonisation of Know Your Customer requirements and greater consistency in regulations across African monetary unions. They said the measures would reduce operational costs, encourage competition and improve access to affordable cross-border financial services. According to the forum, existing settlement arrangements, which largely restrict settlement accounts to banks, place licensed non-bank payment service providers at a disadvantage. The arrangement forces such providers to depend on banking intermediaries for settlement and foreign exchange transactions, resulting in additional delays, liquidity constraints and higher operational costs. The participants therefore recommended expanding access to settlement accounts for appropriately licensed non-bank providers and allowing supervised private sector operators to participate more directly in settlement arrangements. They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
They urged the establishment of a permanent platform for dialogue between regulators and industry players to ensure that policies and regulatory reforms reflect operational realities and emerging market needs. The participants at the event held on July 22, 2026, also called for mutual recognition of licences, harmonisation of Know Your Customer requirements and greater consistency in regulations across African monetary unions. They said the measures would reduce operational costs, encourage competition and improve access to affordable cross-border financial services. According to the forum, existing settlement arrangements, which largely restrict settlement accounts to banks, place licensed non-bank payment service providers at a disadvantage. The arrangement forces such providers to depend on banking intermediaries for settlement and foreign exchange transactions, resulting in additional delays, liquidity constraints and higher operational costs. The participants therefore recommended expanding access to settlement accounts for appropriately licensed non-bank providers and allowing supervised private sector operators to participate more directly in settlement arrangements. They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The participants at the event held on July 22, 2026, also called for mutual recognition of licences, harmonisation of Know Your Customer requirements and greater consistency in regulations across African monetary unions. They said the measures would reduce operational costs, encourage competition and improve access to affordable cross-border financial services. According to the forum, existing settlement arrangements, which largely restrict settlement accounts to banks, place licensed non-bank payment service providers at a disadvantage. The arrangement forces such providers to depend on banking intermediaries for settlement and foreign exchange transactions, resulting in additional delays, liquidity constraints and higher operational costs. The participants therefore recommended expanding access to settlement accounts for appropriately licensed non-bank providers and allowing supervised private sector operators to participate more directly in settlement arrangements. They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
They said the measures would reduce operational costs, encourage competition and improve access to affordable cross-border financial services. According to the forum, existing settlement arrangements, which largely restrict settlement accounts to banks, place licensed non-bank payment service providers at a disadvantage. The arrangement forces such providers to depend on banking intermediaries for settlement and foreign exchange transactions, resulting in additional delays, liquidity constraints and higher operational costs. The participants therefore recommended expanding access to settlement accounts for appropriately licensed non-bank providers and allowing supervised private sector operators to participate more directly in settlement arrangements. They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
According to the forum, existing settlement arrangements, which largely restrict settlement accounts to banks, place licensed non-bank payment service providers at a disadvantage. The arrangement forces such providers to depend on banking intermediaries for settlement and foreign exchange transactions, resulting in additional delays, liquidity constraints and higher operational costs. The participants therefore recommended expanding access to settlement accounts for appropriately licensed non-bank providers and allowing supervised private sector operators to participate more directly in settlement arrangements. They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The arrangement forces such providers to depend on banking intermediaries for settlement and foreign exchange transactions, resulting in additional delays, liquidity constraints and higher operational costs. The participants therefore recommended expanding access to settlement accounts for appropriately licensed non-bank providers and allowing supervised private sector operators to participate more directly in settlement arrangements. They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The participants therefore recommended expanding access to settlement accounts for appropriately licensed non-bank providers and allowing supervised private sector operators to participate more directly in settlement arrangements. They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
They also proposed exploring pilot payment corridors between the West African CFA franc (XOF) and Central African CFA franc (XAF) monetary zones as a practical step towards regulatory harmonisation. The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The fixed parity between the two currencies reduces exchange-rate risks, while existing common legal frameworks in areas such as business law, insurance and intellectual property provide a basis for closer cooperation, the participants said. The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The forum is part of a series of private sector consultations convened by the African Union Commission and the AfricaNenda Foundation, in collaboration with the Association of African Central Banks, since February 2026. The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The consultations are aimed at building consensus on harmonising policies and regulations for cross-border retail digital payments across Africa, rather than establishing a single pan-African payment scheme. The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The findings are expected to contribute to the development of the Regulatory Harmonization Framework for Cross-Border Payment Services in Africa and the work of the AACB Task Force on Payment Systems Integration. The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The forum noted that, despite the rapid growth of digital finance, cross-border payments remained costly, fragmented and slow, limiting their effectiveness for trade, remittances, small businesses and consumers. Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
Cross-border payments in Africa were estimated at $329bn in 2025 and are projected to reach $1tn by 2035. Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
Sub-Saharan Africa also remains the world’s most expensive region for remittances, with the average cost of sending $200 put at about 8.78 per cent, significantly above the Sustainable Development Goal target of three per cent. The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
The participants said a permanent consultation framework, stronger regulatory alignment and improved settlement access were necessary to address the challenges and support regional economic integration. They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share
They urged continued engagement between regulators and industry players to ensure that proposed reforms translate into practical improvements in the delivery of cross-border payment services across Africa. Share